Differentiating savings from additional payment flow
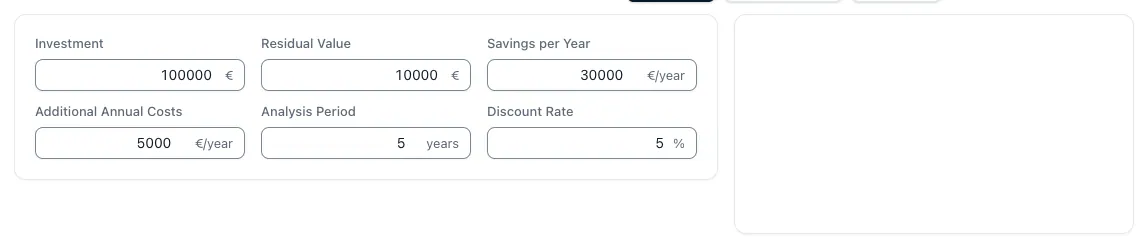
For a comparison, the annual savings and additional running costs resulting from the investment are recorded. The calculator uses their difference as a constant net return. Free machine hours are not automatically a cash saving: It must be clear how the economic benefit arises.
Acquisition, installation and other one-off expenditures are included in the investment amount under consideration. Double depreciation or financing costs already included would change the model.
Calculate static return time
With 100,000 € initial investment, assumed 30,000 € annual savings and 5,000 € additional annual costs, 25,000 € net return remains. The static amortization is four years.
This measure does not take into account any interest rate effect and no backflows after the amortisation date. In the linked computer, a later residual value does not reduce the initial static investment; it is taken into account separately in the net present value at the end of the term.
Annual net = saving – additional annual costs; t_Amortisation = investment ÷ Annual net
Net present value in the same case
For five full years, five percent calculation interest and a residual value of €10,000 at the end of the fifth year, a capital value of €16,072.18 results. The calculator discounts the constant annual net income at the end of each year and the residual value at the end of the last year.
The figure applies exclusively to these assumed cash flows. A positive capital value is a statement within the chosen model, not a guarantee of actual profitability.
Capital value = −Investment + Σ[Annual net ÷ (1 + i)^t] + Residual value ÷ (1 + i)^N
Making limits visible through own scenarios
The computer does not contain automatic control, promotion or financing planning and no annual changing returns. Consider, for example, a lower saving, longer start-up phase or higher maintenance costs with separate scenarios.
If the net return is not positive, no finite static amortisation period is shown. A purchase can not be justified by a freely invented return return period.
Sources and classification
- Robert Leemann / RAVEL: Methods of Economic Analysis of Energy Systems
Guidelines of the Federal Office for Economic Questions, Chapters 4.4 and 5.2; provided by the Federal Office for Energy. The figures on this page are own assumptions.
Questions and answers
Why can amortization and capital value lead to different valuations?
They look at different aspects. The static amortization measures the simple return period; the capital value weights all recorded payments within the chosen term with the calculation interest.
Is the calculated capital value a purchase recommendation?
No. It evaluates your assumptions. Financing, risks, real capacity utilization and alternatives must be additionally assessed.