Counting good quantity and rework clearly
The quantity of goods is the number of processed parts minus final scrap. Successfully reworked parts are already included in this quantity and will not be added a second time.
In case of unsuccessful rework, the part counts as part of the committee. The post-work effort incurred until then must then be included in its committee costs. Otherwise, the same effort would be missing or double.
Evaluate committee only up to the actual progress
An early detection of defective raw material does not necessarily have the same incurred costs as a fully processed part. Therefore, the expenses incurred until detection are recorded for rejects. A net recoverable value actually reduces the loss.
K_Los = Good quantity × Basic costs per good part + scrap × (cost incurred – net recovery) + K_reproduction
Example of calculation with 95 parts
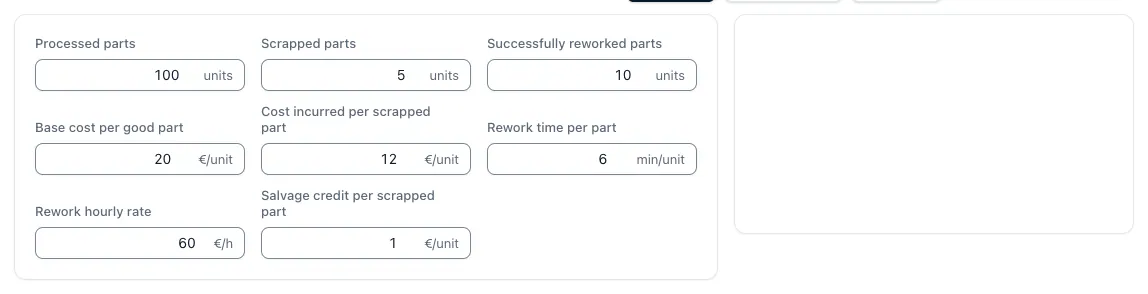
Out of 100 processed parts, five are final scraps; ten of the 95 goods have been successfully reworked. Basic costs per good: 20 €. Per scrap has been incurred 12 €, at 2 € net recycling. This results in 50 € net loss of committee.
Ten post-work parts with six minutes each at 60 €/h cost an additional 60 €. The lot costs are 95 × 20 € + 50 € + 60 € = 2.010 €. Distributed to 95 good parts are around 21,16 € per good part. 85 out of 100 parts were good without rework: 85%. The values are a freely chosen calculation example.
Recalculation and distinction between future offers
The result describes a lot with actually incurred quantities and costs. A future offer requires a justified own assumption about errors and rework. A single lot deviation is not unchecked to become a permanent lump sum.
Test costs are considered separately, provided they are not already included in the basic costs. The operational evaluation does not replace an accounting allocation of different types of loss.
Questions and answers
Are reworked parts added to the quantity of goods?
No. Successfully reworked parts are already part of the quantity of goods. The calculator only adds the additional post-work costs.
What happens with a complete committee?
There are no good parts on which the costs could be distributed. Costs per good are then not determinable; the loss of the lot remains nevertheless relevant.